Residual Value Is Holding Back Electric Fleets. Insurance Can Help.
A recap of GreenieRE's EV RVI Workshop at NY Climate Week
There’s a case to be made for commercial electric vehicles. Replacing a single commercial diesel vehicle with an electric equivalent can prevent as much as 1,000 metric tons of greenhouse gases from being emitted over the vehicle’s life. And with diesel prices continuing to climb, trucking fleet operators are feeling the pressure. Nevertheless, zero-emission commercial vehicles have been unable to deploy at-scale. One of the reasons? Low predicted residual values.
For commercial truck and bus fleets to be financially successful, they must reach Total Cost of Ownership (TCO) parity with diesel vehicles. The biggest component of fleet TCO is often the lease payment, and residual value is one of the main pricing factors. A higher residual value results in lower monthly lease payments.
Since EVs are a relatively new technology, lessors often set residual values near zero. Even though these vehicles will have value at the end of the lease term, the lack of resale history data prevents lenders from assigning more accurate valuation figures, resulting in prohibitively high lease payments for fleet owners.
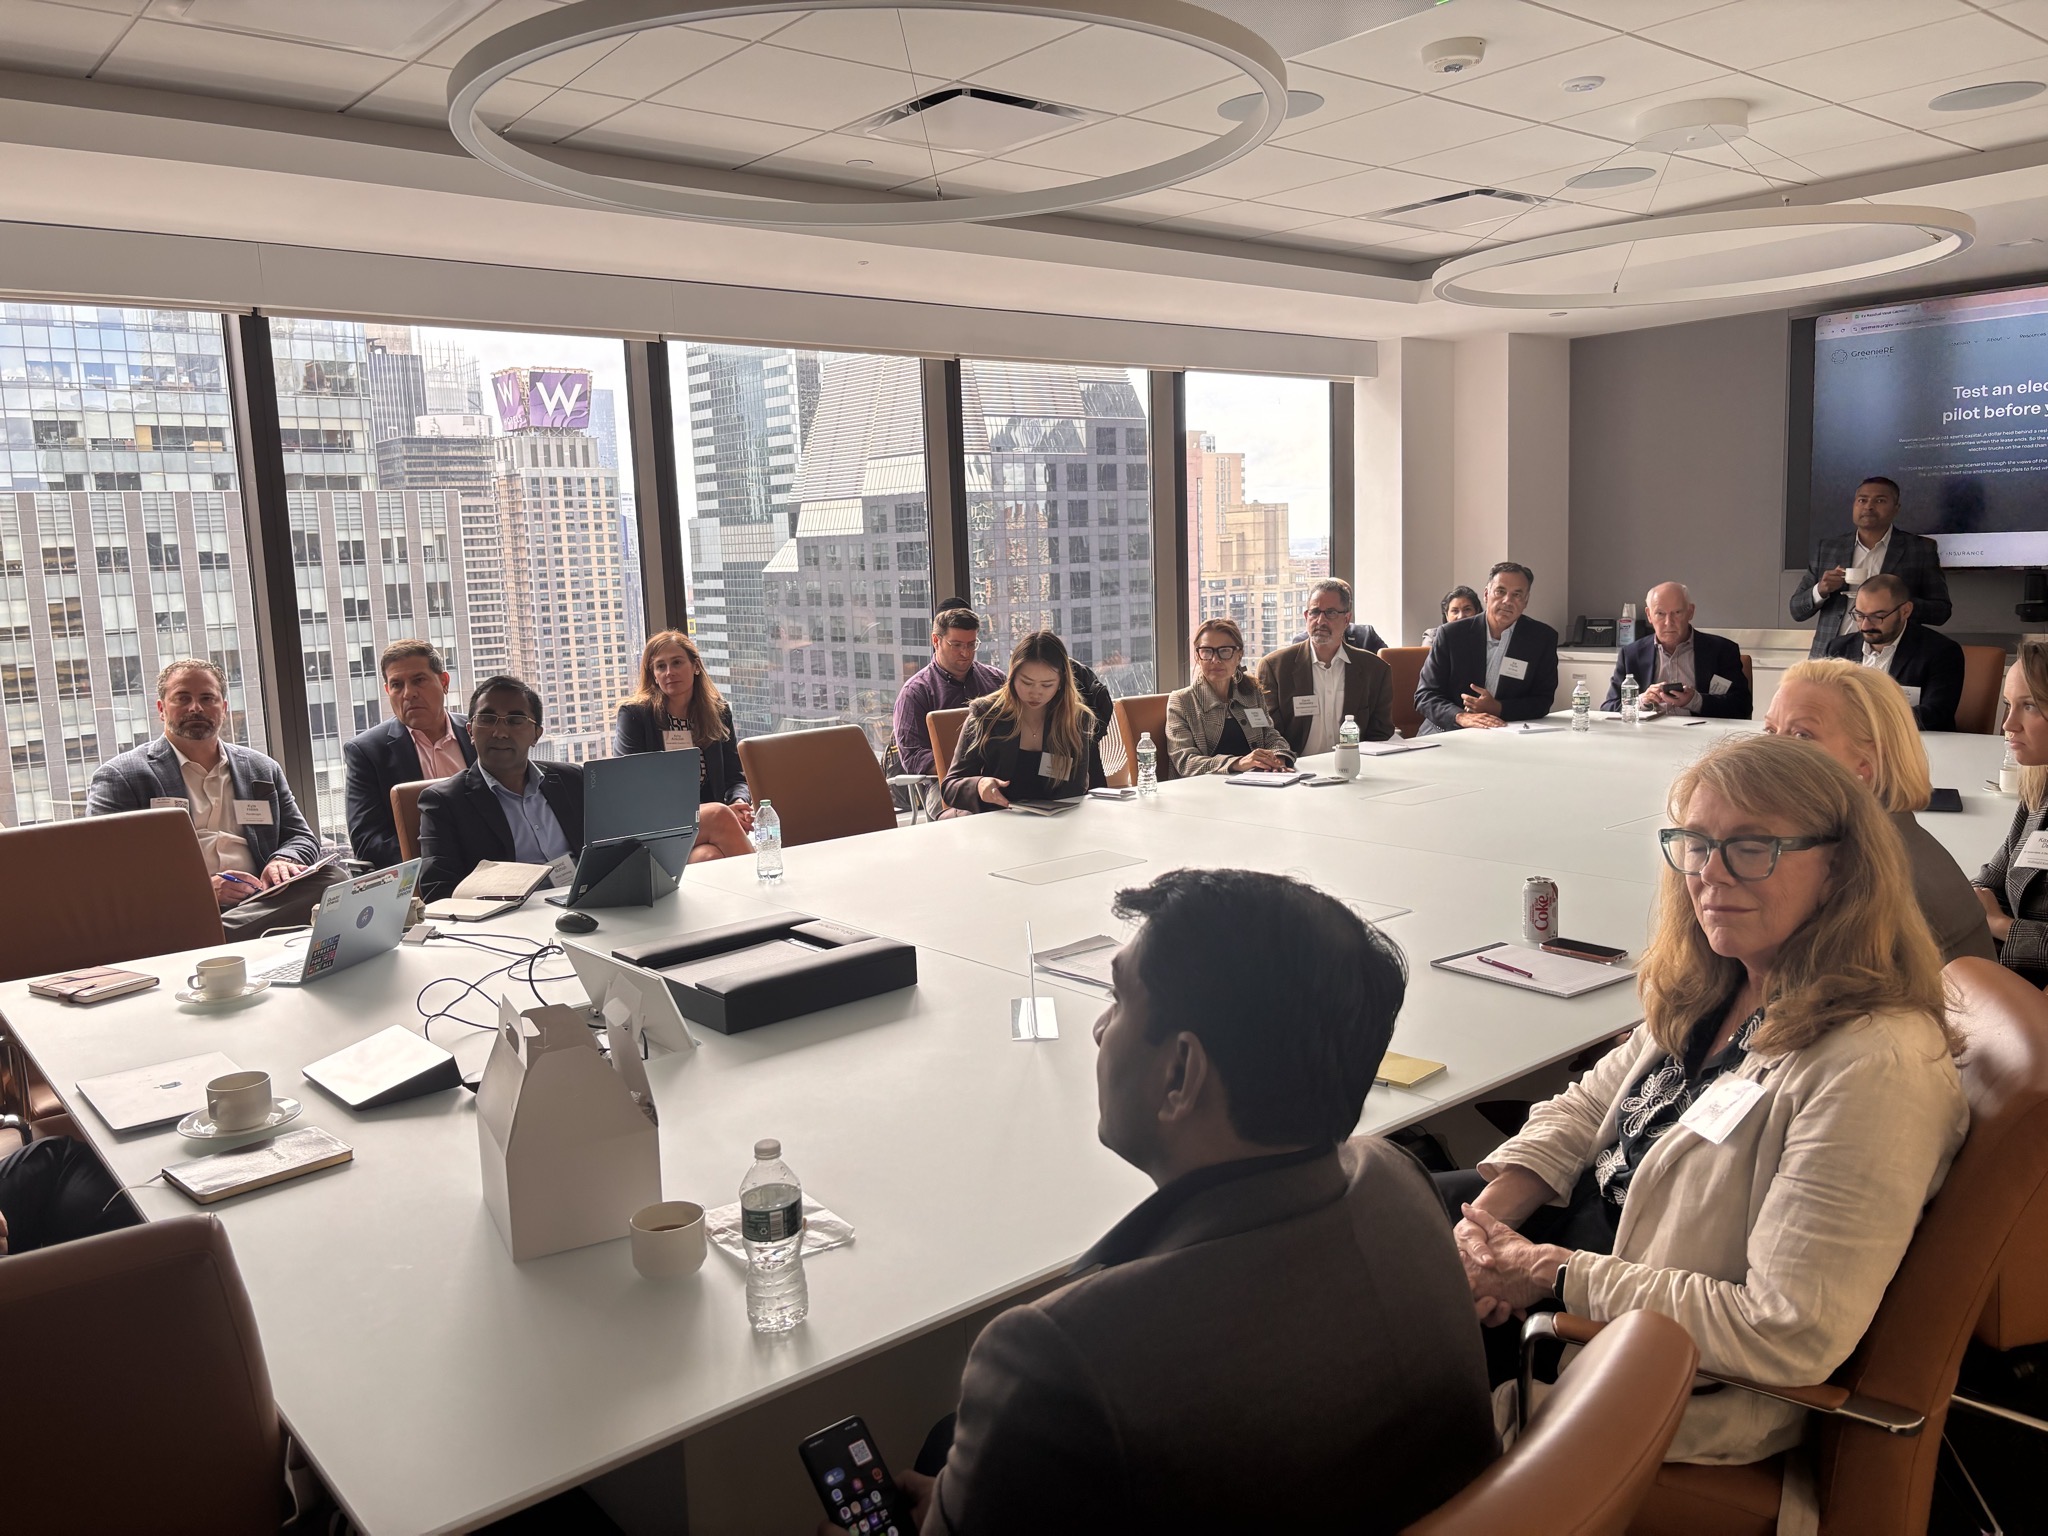
This is where insurance can help, and we took the first step toward making this vision a reality at a GreenieRE-hosted EV residual value insurance (RVI) workshop during NY Climate Week 2026.
Nearly 50 people — including representatives from fleet leasing companies, insurance brokers, insurers, MGAs, state agencies, think tanks, vehicle OEMs, traditional financiers, and catalytic capital — all huddled into a conference room to discuss how TCO parity can be achieved for medium- and heavy-duty electric trucks that have a higher sticker price than their diesel counterparts. We know that RVI has the potential to bridge the sticker price gap by enabling lower lease costs, but in what situations could it beat traditional diesel? This was the question on the table.
To help facilitate more productive discussions, GreenieRE built a tool to enable participants to dig into the quantitative differences of each use case and focus purely on the metrics at hand. With this tool, participants were able to cut to the heart of the matter and see the impact in real time.
In addition to identifying the percentage of RVI needed to achieve TCO parity — which was reinforced by research from Calstart and the Smart Freight Centre — the workshop also highlighted how critical it is to find a way to blend both public and private impact capital to create a solution that benefit businesses, the broader community, and our environment.
Loan loss reserve contracts are too complex and heterogenous, the assembled participants agreed, making it difficult to create a one-size-fits all financing arrangement. But standardized financial insurance structures and proven insurance policy forms can help. By working through traditional insurance channels, fleets and leasing companies can buy insurance policies to blend public and private capital within a ‘risk tower’.
Our thesis was validated: Insurance is the key to getting more commercial electric vehicles on the road. So, we’re developing an EV RVI pilot program that will create an instrument for transferring residual value risk and an initial loss history for commercial underwriters to price.
If you’re interested in getting involved with the pilot program, we encourage you to reach out at info@greeniere.org. We also encourage you to try out our EV RVI tool for yourself so you can see the impact RVI can have: https://greeniere.org/ev-residual-value-calculator.